One of the questions I hear most often from buyers and sellers is, “How much will I actually need to pay at closing?” The purchase price or expected sale price is only part of the financial picture. Closing costs can add a meaningful amount to a transaction, and they can vary depending on the property, financing, location, and terms of the deal. I always encourage clients to understand these expenses early rather than waiting until the final days before closing. When you know what to expect, you can budget more comfortably, evaluate offers more confidently, and avoid unpleasant surprises when it is time to sign the paperwork.
What Are Closing Costs?
Closing costs are the various expenses involved in completing a real estate transaction. For buyers, they can include lender fees, appraisal costs, title services, recording fees, prepaid taxes, homeowners insurance, and other expenses associated with purchasing and financing the property. Sellers may have costs related to commissions, transfer taxes, title services, mortgage payoff, property taxes, and negotiated credits or repairs. The exact expenses will depend on the transaction, which is why I recommend asking for a detailed estimate early in the process instead of relying on a general percentage or online calculator.
What Buyers Should Budget For
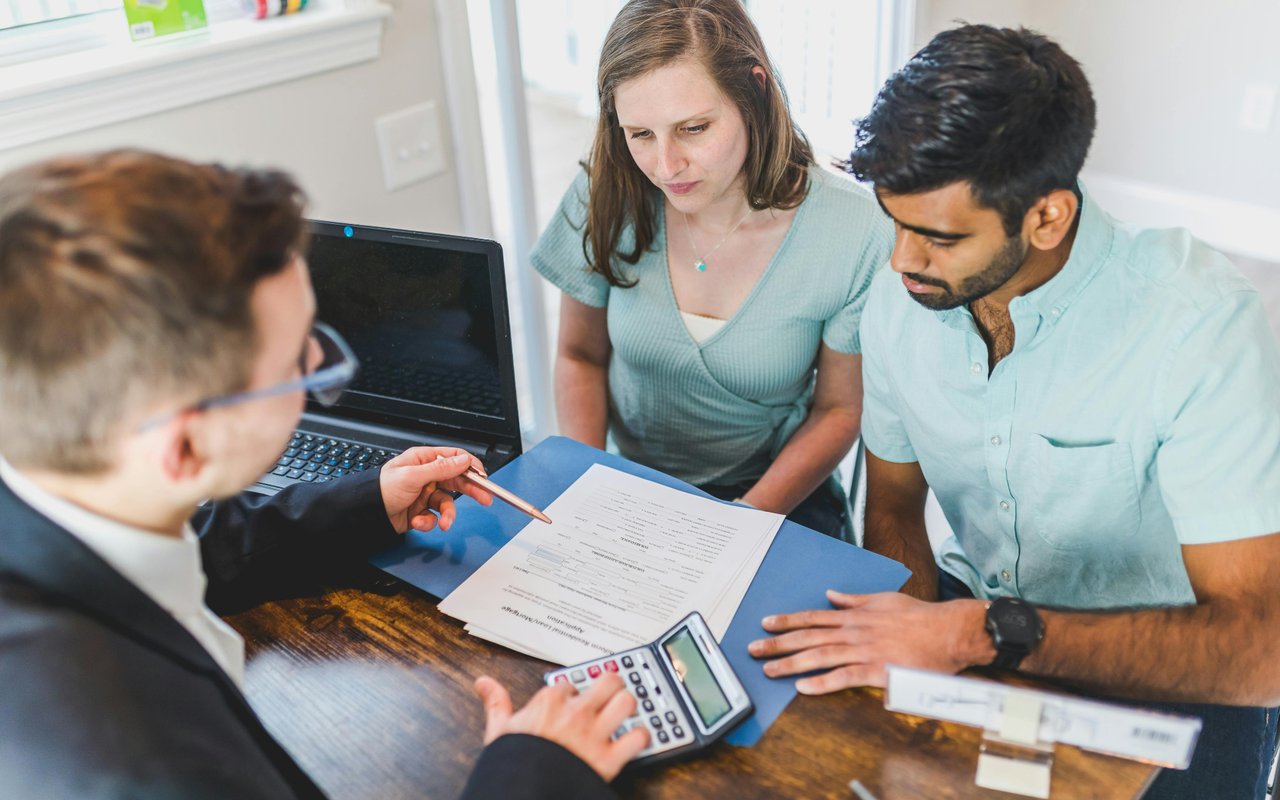
For buyers, one of the biggest mistakes is planning only for the down payment and forgetting about the other money needed to get to the closing table. Your lender should provide a detailed estimate of your expected closing costs, but it is also important to understand that some expenses may be prepaid or placed into an escrow account. I encourage buyers to look at the full amount of cash they will need, including their down payment, closing costs, moving expenses, and a financial cushion for unexpected costs after moving in. Buying a home should leave you feeling financially comfortable, not stretched to the limit on day one.
What Sellers Should Expect to Pay
Sellers often focus on how much their home will sell for, but the final sale price does not necessarily equal the amount they will take home. Expenses such as real estate commissions, transfer taxes, title-related fees, outstanding property taxes, mortgage payoff amounts, and agreed-upon buyer credits can reduce the final proceeds. Before putting your home on the market, I recommend reviewing a projected seller net sheet with your real estate professional. This gives you a much clearer idea of what you can expect to receive after the transaction costs are accounted for and can help you make smarter decisions about pricing and your next purchase.
Can Closing Costs Be Negotiated?
Closing costs are not always divided between the buyer and seller in exactly the same way. Depending on the transaction and applicable lending rules, the parties may be able to negotiate certain expenses or seller credits toward eligible buyer costs. These negotiations can become especially important when market conditions change. A buyer may request assistance with certain costs as part of an offer, while a seller may consider that request alongside the offer price and other terms. Rather than looking at one number in isolation, I encourage clients to consider the entire offer and understand how each term affects their bottom line.
How to Prepare for Closing Costs
The best way to avoid surprises is to start planning for closing costs before you are under contract. Buyers should ask their lender for an updated estimate and make sure they understand how much cash they will need at closing. Sellers should request a projected net proceeds estimate that accounts for the expected sale price and anticipated expenses. I also recommend keeping some extra room in your budget because certain costs can change as the transaction progresses. If you are considering buying or selling, having a conversation with your real estate professional early can help you understand the numbers, prepare appropriately, and move toward closing with greater confidence. The more you know before the transaction begins, the easier it is to make decisions that support your financial goals.